Ziki Ye | October 2026 market report
Mortgage rates and your next move | Oct.2026
My take on mortgage rates, condo loans, and planning for 2027
At a glance
- Buyers: If you're not in a rush, I'd wait until early 2027 to start house hunting. On Oct 1, 2026, the national 30-year fixed rate hit 7.28%, its highest weekly average of 2026 so far. Fannie Mae expects it to ease a little in 2027 compared with late 2026. I've also compared Bay Area listings, sales, and days on market in 2026 with 2025, and that research supports waiting. If you're looking at condos, tell your lender during preapproval and give them extra time to review the HOA and building documents during closing. When writing an offer, allow for that review in your closing date and loan contingency deadlines to help protect your earnest money deposit.
- Sellers: I think the Bay Area market is slowing as 2026 winds down. If you can wait, I'd get your documents and inspection reports ready now and list in 2027. For a condo, gather the HOA budget, reserve study, insurance, and repair records for buyers' lenders.
Today's rates
- The average rate rose to 6.86% in Sept. 2026. It was 6.05% in Feb. 2026 and 6.35% in Sept. 2025. [1]
- On Oct 1, 2026, the weekly average reached 7.28%, up from 7.03% the week before. This is one week's reading, not a full-month Oct. average. [2]
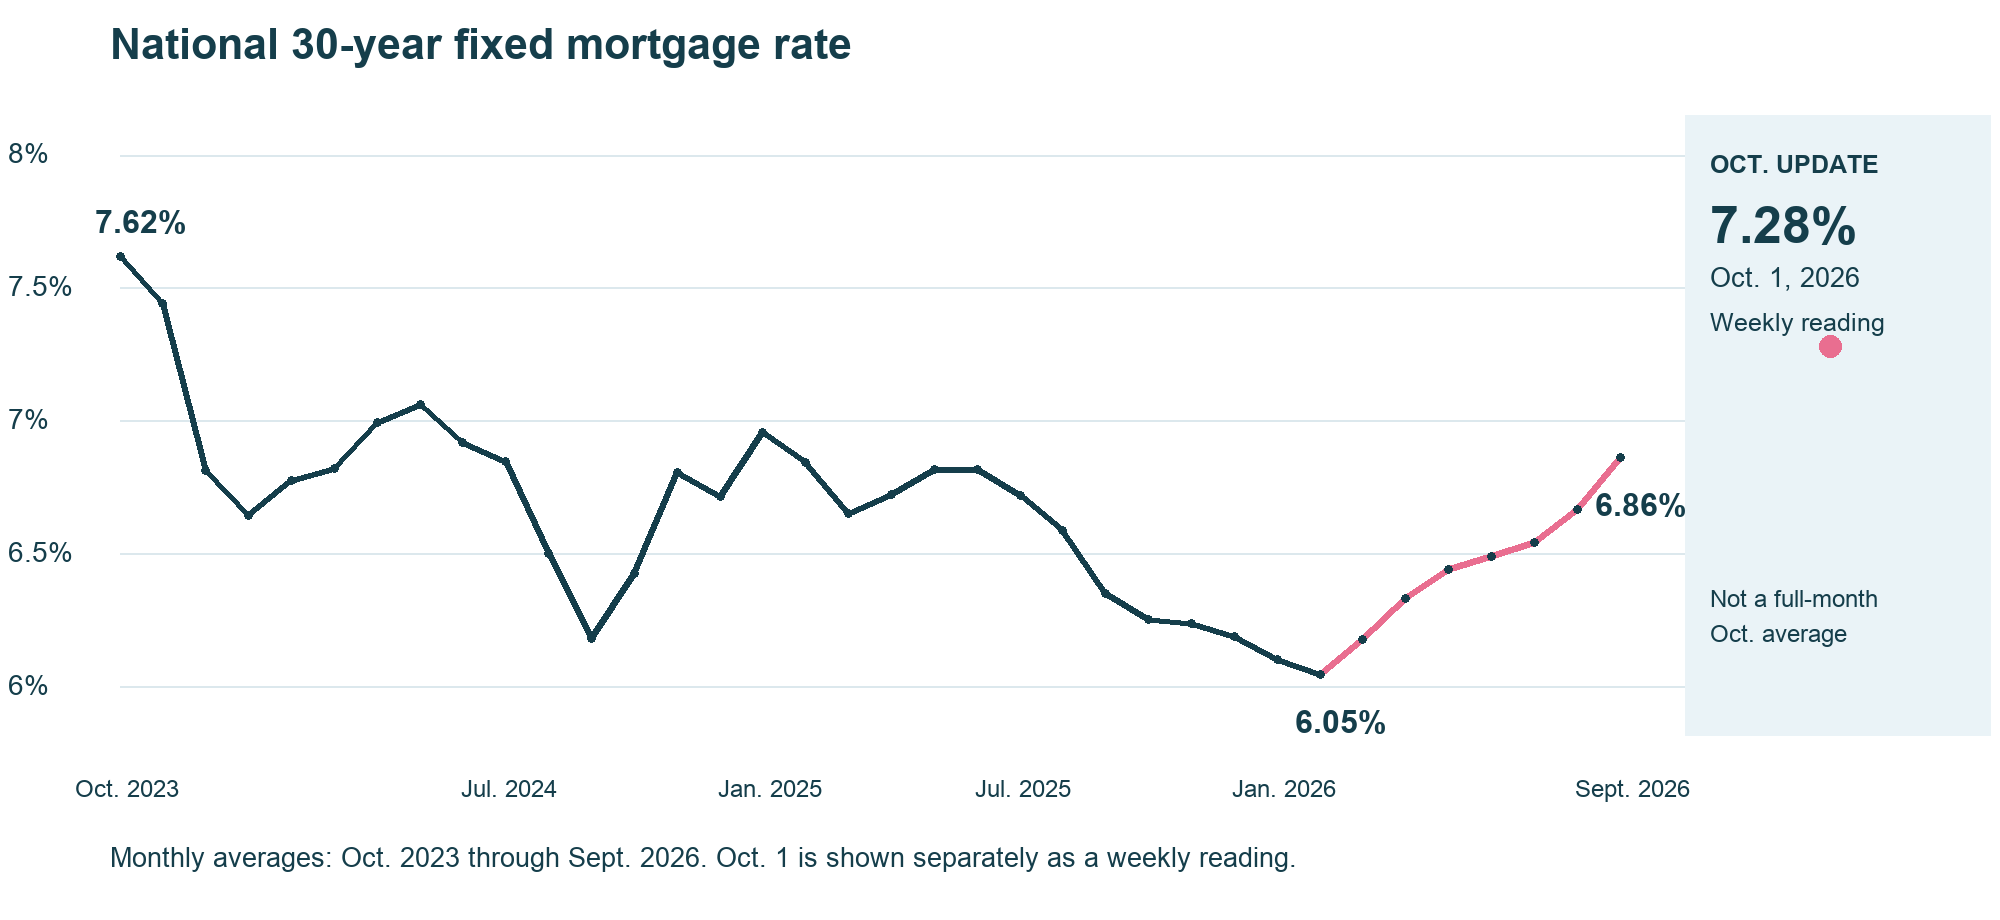 View full-size chart (new tab)
The line shows 36 monthly averages. The Oct. panel shows the latest weekly reading separately, because Oct. isn't complete. Your Bay Area jumbo or condo quote may differ.
My take: rates may ease in 2027 vs. late 2026
- Higher yields on U.S. government bonds helped push mortgage rates up. Expectations for economic growth, inflation, and policy also contributed. [4]
- Fannie Mae forecasts the national 30-year fixed rate to average 6.8% in Oct. through Dec. 2026, then 6.7% in each quarter of 2027. [6]
- My take: this supports patience, not a promise of cheaper loans in early 2027. The forecast compares late 2026 with 2027 quarters, not matching months. It predates the latest weekly jump and may change. [6]
Condo mortgages may be harder to get approved
My take: leave extra time for condo financing. Both the borrower and the building must qualify. Fannie Mae's changes cover building reviews, HOA reserves, and small-building exceptions. They don't make every condo ineligible or establish Bay Area denial rates. [5]
- The building review is changing. Limited Review ended for applications starting Aug 3, 2026. Established projects now need the more detailed Full Review or a qualifying waiver. [5]
- HOA reserve budgets face a higher standard. For applications starting Jan 4, 2027, the standard Full Review reserve allocation rises from 10% to 15% of annual budgeted income assessment, not property value. A qualifying reserve study can provide an alternative, but it must support the highest recommended allocation. [5]
- Small buildings have an exception. Qualifying projects with ten or fewer units may use expanded review waivers. Five-to-ten-unit projects can't belong to a master association or larger development. Insurance requirements still apply. [5]
Sources and further reading
[1] Freddie Mac weekly data | Monthly chart calculations
[2] Freddie Mac latest release | 7.28% weekly rate
[4] Reuters | Latest jump and its drivers
[5] Fannie Mae LL 2026 03 | Condo review and reserve rules
[6] Fannie Mae Sept. 2026 forecast | Rate outlook
[7] Axios Chicago | Condo sales concerns (not Bay Area denial data)